

Unleash Prosperity held its 10th anniversary gala in Washington this week, featuring the conversation format that haunts my nightmares: the five-man panel.
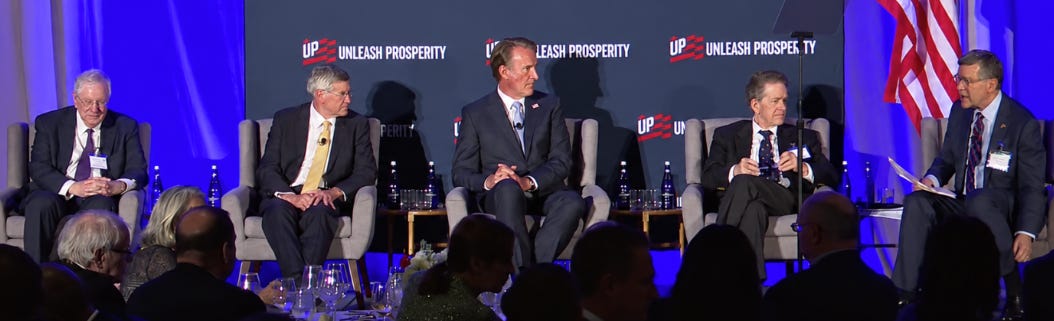
(photo credit: Washington Free Beacon)
The Washington Free Beacon reports that founders Steve Forbes, Steve Moore, and Art Laffer joined former Virginia Governor Glenn Youngkin and Fox News’s David Asman to discuss a range of policies including lower taxes, a flat tax, tax simplification, cutting the capital gains tax, and eliminating the estate tax. Also, in Youngkin’s words, to “reinstill hope.”
The Beacon suggests three possible interpretations:
“This supply-side wing is a bunch of has-beens, aging relics of the Reagan past. Laffer is 86, Forbes and Kudlow are 79.” (Their words, not mine.)
“The Unleash Prosperity crowd has been actually far more influential in Trump economic policy than has been widely understood or appreciated,” helping shape tax cuts.
“A third way to look at it is that the pro-growth, free market approach has room to run in a post-Trump Republican Party. Of the key agenda items enumerated at the gala—school choice, a Steve Forbes flat tax, technology dominance, and Social Security reform with private accounts—there is plenty left to cover in the future.”
These observations are not mutually exclusive. Rather, they might be best read in a sequence of 2, then 3, then 1. The supply-siders have been influential in shaping Trump-era tax cuts. But their “key agenda items” of school choice, a flat tax, and privatizing Social Security are relics of the GOP past. (No, “technology dominance” is not an agenda item.) There is always “room to run” off the road’s side and into a dried-out ditch, but that prospect is usually reason enough to take away the keys.
GOOD READS FOR YOUR WEEKEND
The Wall Street Journal’s feature on the Savannah Bananas is self-recommending, but it has important lessons for The Real Economy too!
In the rise of Banana Ball, it’s not hard to see a rejection of the crass price-gouging that’s overtaken professional and even college sports. Cole has designed a Bananas outing to be rigorously affordable. Tickets for Banana Ball games at major league parks start at $30 and peak at $60—not enough to park your car at a lot of pro sports events. Tickets at Grayson come with all-you-can-eat food and sodas. Cole even launched a bespoke Bananas ticket exchange so fans could sell directly to fans and avoid the exorbitant reseller market that many teams and leagues partner with.
…
For all the current mania, Cole insists on playing the long road. He’s got plenty of ideas in the pipeline—a Bananas cruise; a game with two diamonds; a possible international tour—but he’s wary of saturation and strives to keep Banana Ball accessible. He insists that ESPN’s arrangement allows the games to also be shown for free on YouTube. Cole even broke ties with a handful of sponsors after deciding they didn’t feel very Banana Ball. He’s resisted multiple offers to sell; he and Emily still wholly own the franchise.
At Labor Innovation, David Rolf looks Beyond the Next Wave Election: Rebuilding Worker Power for the Long Haul. “We don’t require every family to organize its own school district or every neighborhood to negotiate separately for power lines or police protection. Why should workers have to organize employer by employer to secure a meaningful collective voice in the economic decisions that shape their lives?”
In the New York Times, Julia Stiles’s Dancing Is Healing Millennials. Cheers to the Times for giving us the in-depth coverage we needed of her poignant tribute to Heath Ledger on Dancing with the Stars. Jeers, though, for referring to 10 Things I Hate About You as a “cult classic.” Do we refer to The Godfather as a cult classic? The Shawshank Redemption? Zoolander? I didn’t think so.
And speaking of Elder Millennials, you must read Chris Griswold’s new policy essay for American Compass on Vocational Education for All. I predict this proposal for universal voc ed will soon become conventional wisdom, and his essay the seminal case. Chris also joins me on this week’s episode of the American Compass Podcast to discuss further.
OH WHEN WILL THEY EVER LEARN?
The economists and pundits who led the American economy off the globalization cliff will often hide behind the defense that they could not possibly have known how China was going to undermine the hypothetically wonderful rules-based international order. In fact, they should have known and, more importantly, they did not care. The market fundamentalism of the consumer-welfare-maximizing free-traders insists that it does not matter what other countries do, all that matters is getting cheaper stuff.
(And yes, I will once again quote Paul Krugman, until you have all memorized the line, “a country serves its own interests by pursuing free trade regardless of what other countries may do.” And yes, I will once again remind you that this is still the conventional wisdom at the American Enterprise Institute.)
Lest one have any doubts, even as a publication like The Economist sounds the retreat on the principle applied to industrial capacity (“Foreign companies, however big, stand little chance against a Leninist developmental state that has attained China’s size, wealth and modernity.”), it is charging straight into the same ambush on the next technological wave.
In Let China copy American AI, The Economist even recognizes the pattern and proposes that we repeat it:
Anthropic and OpenAI have lately taken up an old tradition in corporate America: bemoaning the Chinese copycat. For decades firms moved assembly lines to China only to find me-too merchants rising next door. Now America’s leading artificial-intelligence labs say the same thing is happening to their models, and want the federal government to stop it.
…
Yet the labs’ commercial interests do not align with those of consumers. Users win when there are more—and more capable—models on offer.
…
Policymakers in Washington should recognise what Chinese AI bosses already do: the technique makes China’s progress dependent on America.
Yes, China is running the exact same playbook. Yes, we should again thank them for undercutting our innovators with cheaper consumer products. And yes, we still believe that we are going to secure long-term leadership by hooking China on our technology. What could go wrong?
It’s not like China is actively compromising the leaders of our top tech firms to… Nvidia Chief Seen as Target of Chinese Spy Plot (New York Times):
A top executive at a Singapore-based data center company was under scrutiny for possibly steering advanced Nvidia A.I. chips to China. And now American officials had concluded that she was a Chinese intelligence asset, funneling information to Beijing.
But what came next was even more alarming. Surveillance of the executive, Alice Huang or Huang Le, a Chinese citizen, revealed that she had developed a close relationship with Jensen Huang, Nvidia’s chief executive.
One might hope this would lead Huang to update his view of the Chinese Communist Party, that “they want companies to come to China and compete in the marketplace and I believe that. … I do hope because they say it—their leaders say it. And I take it at face value.” Somehow I doubt it.
THE FOUR STAGES OF TARIFF GRIEF
In The Art of the Tariff, Politico helpfully highlights the morass of arguments that tariff opponents now find themselves throwing mostly at each other.
Stage 1: We don’t need manufacturing.
“The economy has over time moved from being entirely agricultural to having a footprint in manufacturing, and now it’s got an enormous productive service sector,” Holtz-Eakin said. “I don’t see the need to focus on [manufacturing] the way both administrations have. It seems like more nostalgia than good economic policy.”
Stage 2: Manufacturing isn’t booming.
Berger said she still sees the merit in preserving a large manufacturing sector to maintain the U.S.’s innovation edge, supply chain resiliency and national security. But she argued that Trump’s trade policies, including frequent tariff shifts, aren’t going to herald a revival, despite what the president is telling voters. “I don’t see any sign of it,” she said.
Stage 3: We are seeing a manufacturing boom, but tariffs make it harder.
“When all is said and done, you can’t really point to the tariffs,” Douglas Holtz-Eakin, president of the American Action Forum, a center-right Washington-based think tank, told Morning Trade. “It’s a wash at best, but I would think that on the whole, they would be a hindrance” to manufacturing growth.
Stage 4: Yes, tariffs help. But at what cost?
This is the one we’re now arriving at, as evidence for any of the first three collapses. And it has the benefit of being correct. Yes, tariffs will drive reindustrialization. And yes, that has costs. Welcome to the wonderful world of trade-offs. The question, of course, is what those benefits and costs are in the long run, which is what sends opponents running back to the first stage, disclaiming that we should be willing to incur any costs in the first place. It’s a nice tight loop of internal coherence that works so long as it avoids contact with reality.
Meanwhile, in the real economy, new industrial expansions keep rolling in:
First Solar: “Today Governor Henry McMaster, Senator Darlene Graham, Commerce Secretary Howard Lutnick, and South Carolina officials joined us to inaugurate our newest facility in Gaffney, South Carolina. This is a working factory, not an empty shell, with 500 people employed and 700 jobs expected in 2027. It exists because the moment demanded it. The One Big Beautiful Bill Act and the Trump Administration’s trade policies drove real demand for American energy technology, and we moved to onshore final production as rapidly as we could.”
U.S. Steel: “U. S. Steel’s Board of Directors has approved full funding for a nearly $3 billion investment in a new hot strip mill at the company’s Mon Valley Works – Edgar Thomson Plant near Pittsburgh.”
Anduril and Qualcomm (via PirateWires): “Defense technology company Anduril and semiconductor firm Qualcomm launched an initiative to produce 100% made-in-America computers. Today, the companies announced BlueChip, a product line ‘dedicated to rebuilding American computer manufacturing’ and reducing dependency on foreign manufacturers, according to a press release, beginning with a laptop set for release next year.”
Volkswagen (via Wall Street Journal): “Audi and Porsche are the only German auto brands without a U.S. factory. Their corporate cousin Volkswagen, and direct rivals BMW and Mercedes-Benz, all produce cars in factories across the South, in some cases for global export. That situation has left Audi, which primarily builds its U.S.-market cars in Germany, Mexico and Central and Eastern Europe, particularly vulnerable to tariffs in Trump’s second term.”
Which brings us to…
YOUR GERMAN GOOSE(STEP) OF THE WEEK
From Politico Europe: “Disturbing and pathetic”: German politicians slam Audi CEO’s appearance at Trump rally. “German politicians have sharply criticized Audi CEO Gernot Döllner’s appearance alongside U.S. President Donald Trump at a campaign rally on Saturday. ‘Actively campaigning for an autocrat who is waging a trade war against Germany marks a new low for the VW Group,’ said Isabel Cademartori, a Social Democratic Party lawmaker and the party’s transport policy spokesperson.”
With due respect to Ms. Cademartori, probably best to avoid phrases like “new low” when discussing a corporation whose history page features lines like: “The US troops who arrived on April 11, 1945 stopped the plant’s armaments production and liberated its slave workforce. The longed-for end of the Nazi dictatorship marked the beginning of a new era for Volkswagen too.”
We do appreciate, though, her acknowledgment that Audi is “validating Trump’s strategy [of] using a trade war to shift jobs from Europe to the United States.”
WHAT COULD GO WRONG?
Our financial sector continues to find new ways to earn money while creating no value and indeed making life worse, which, when you think about it, is actually a pretty impressive feat. You’ll recall recent The Real Economy coverage of the “tax-aware long-short” strategies seeking to avoid capital gains taxes, but that’s a few hundred billion dollars.
Now, the Wall Street Journal delivers a helpful primer on The ‘Buy, Borrow and Die’ Wealth Strategy Has Become a $5 Trillion Market. Let’s say you’re asset rich, your stocks have gone up, but if you sell them you’d have to pay taxes. Instead, you go borrow money from a bank, posting your stock as collateral, and can consume whatever you want tax-free. When you die, you pass along your assets, which get “stepped-up basis,” and no one ever pays taxes on the gains. The Journal goes to great lengths to find legitimate reasons this might be useful, but in fact it is just tax avoidance bordering on tax fraud.
And it’s actually kind of risky. People are “levering up” their personal balance sheets, which works as long as the market keeps going up, but what happens if it goes down? And what happens if banks start trying to push this model on larger and larger segments of the population? You know, like Monument Bank in the UK, which wants to make sure investors with a few hundred thousand dollars can “adopt a billionaire mindset.”
Then flip on over to the New York Times to read that Baby Boomers Are Retiring in Droves. Private Equity Is Waiting. From the headline, I figured they meant PE is waiting to suck up their savings and charge high fees for sub-market returns. But here we’re talking about how retiring small business owners are selling. “Deal by deal, ownership is being extracted from the thousands of communities where businesses were built to the handful of cities where capital is already concentrated. For the new owners, the primary, and often exclusive, connection to the community is the profit they can derive from the acquired asset.”
But at least it’s efficient? The thing about coin-flip capitalism is that, about half the time, the coin lands tails. We’re seeing this now in private equity, where a gush of deals in the early 2020s, all backed by enormous amounts of debt at low interest rates, all premised on selling the companies in about seven years, now find themselves in a high interest rate environment where no one wants to buy the companies and refinancing the debt is expensive. Oops. If the goal were to actually buy companies, improve them, and then sell them, this might still work fine. But when success relies on macroeconomic conditions outside your control, you get to walk around looking like a genius while the times are good and then… well, thing is, when things go bad, you still get to walk away with all the profits from when times were good. Someone else gets left holding the bag. The Wall Street Journal provides a good illustration in A $300 Billion ‘Debt Wall’ Is Looming Over Private-Equity Backed Companies.
On a lighter note, just an amazing quote in this Bloomberg story, Anthropic’s Massive Revenue Surge Comes With Ballooning Computing Bill, which reports that “Anthropic’s revenue for first half of 2026 is nearly 400x that of its revenue for all of 2023.” Not bad. But Jim Lebenthal, chief market strategist at Cerity Partners, says “frankly, I’d like to see higher revenue growth than what I’m seeing in the filing.”
AND OF COURSE, YOUR CANADA GOOSE OF THE WEEK…
Last week, we took a look at Ezra Klein’s analysis that Canada’s rebuke of the United States has been “ruinous and revealing about the shambles of Donald Trump’s foreign policy — how what Trump is doing is not getting America what Trump wanted. I mean, Trump wanted Canada to be the 51st state. Instead, it might become an associate member of the European Union.”
But nope, EU scraps ‘associate member’ offer for Canada (Politico Europe). Rather, the EU is “opting instead for softer language promising ‘ever closer association’ ahead of a landmark EU-Canada summit.” One thinks of Dwight Schrute’s dream of being Assistant Regional Manager, and his actual title of Assistant to the Regional Manager.
Surprising no one, Prime Minister Mark Carney has proudly seized the Schrute mantle. “The good news is it doesn’t matter about specific names or nomenclature,” he said. “What matters is the difference that it will make to lives of Canadians.” Well no, actually, associate membership in the EU and warm-fuzzy association bear no relationship to one another. Carney still seems to think that Davos posturing is what makes a difference for the lives of Canadians, but he is going to discover that the actual structure of economic relationships matters a lot more.
Enjoy the weekend!
History has shown, over and over, that none of those ideas work. Adam Smith said demand is the only reason for production. You want growth? Increase demand.
As for school choice, one has to ask how much chronic underfunding has had to do with poor performance. Public schools have, can, and do perform very well, if they are not starved for funds. Start with the classroom, the school, then everything else.
You are correct that flat tax and privatization of SS are relics but I think you are wrong about school choice. Public schools have catastrophically failed Americans and nobody worse than minorities. It's a potent issue. As a C-suite guy in a large urban district, it was impossible not to notice the enthusiasm exhibition by charter school parents. This engagement is of huge benefit to their children.